Bank of Canada Raises Interest Rate to 2.50%: Market Update for Buyers and Sellers

On October 28, 2026, the Bank of Canada announced a 25-basis-point increase to its target for the overnight interest rate, bringing it to 2.50%. The Bank Rate is now 2.75%, and the deposit rate is 2.45%.


The decision comes as Canada's economy shows stronger-than-expected growth, while persistent energy price increases and global uncertainty continue to put pressure on inflation. With rising business costs and inflation expected to remain elevated for longer, the Bank has increased its policy rate to help keep inflation under control.


For homebuyers, homeowners, and sellers, this latest announcement provides an update on Canada's economic outlook and the factors that may influence borrowing costs and real estate market conditions.


Global Economic Conditions Remain Uncertain


Global economic activity has remained resilient since the Bank's July Monetary Policy Report, despite higher energy prices and ongoing geopolitical tensions.


In the United States, economic growth continues at a strong pace, supported by consumer spending and investment in artificial intelligence. Growth in the euro area has also remained steady, while China's economy rebounded in the third quarter, supported by strong exports and increased government spending.


However, persistently high oil prices have contributed to rising inflation in many countries. Global financial conditions have also tightened, with higher government bond yields and volatility in financial markets reflecting continued uncertainty.


The Bank now expects global economic growth of 3.1% in 2026 and 3.2% in both 2027 and 2028.


Canada's Economy Shows Stronger Growth


Canada's economy gained momentum through the middle of 2026, with gross domestic product (GDP) growing by 3.3% in the second quarter. Recent indicators suggest growth of approximately 2% in the third quarter, stronger than the Bank had anticipated in July.


Consumer spending has remained solid despite slower population growth. Business investment has also rebounded, supported by activity in the oil and gas sector and increased spending on machinery and equipment.


Exports have strengthened, reflecting robust US demand, higher energy production, and signs that Canadian businesses are adapting to changing trade conditions. However, sectors affected by US tariffs continue to face challenges.


The labour market remains relatively soft, with the unemployment rate holding around 6.5% for several months.


Looking ahead, the Bank expects economic growth to slow in the fourth quarter of 2026 before picking up again in 2027. Canada's economy is projected to grow by approximately 1% in 2026 and 2% in both 2027 and 2028, although uncertainty surrounding Canada-US trade relations remains a key concern.


Inflation Remains a Key Concern


Inflation continues to be an important factor behind the Bank of Canada's latest interest rate decision.


Consumer Price Index (CPI) inflation has remained around 3% since April, largely due to persistently high energy prices. The Bank expects inflation to rise to approximately 3.5% by the end of 2026.


Excluding gasoline, inflation was 2.2% in September, while the Bank's preferred measures of core inflation remain close to its 2% target.


However, higher fuel prices are increasing transportation and production costs, while imported industrial and electronics components have also become more expensive. Businesses may pass more of these costs on to consumers over the coming year.


The Bank now expects inflation to average approximately 3% in 2027 before gradually returning to 2% by the middle of 2028.


In response to these persistent inflationary pressures, the Bank raised its policy rate to 2.50%. It has also indicated that further increases may be possible, although future decisions will depend on economic conditions and how inflation develops.


What Does This Mean for the Real Estate Market?


The Bank of Canada's rate increase may influence borrowing costs and housing affordability, although the impact will vary depending on mortgage type, lender decisions, and individual circumstances.


Variable-rate mortgage holders may be affected if lenders adjust their prime rates, while fixed mortgage rates are influenced more heavily by bond yields and market expectations.


For prospective buyers and homeowners approaching mortgage renewal, borrowing costs remain an important consideration. Meanwhile, sellers will continue to be influenced by buyer demand, property prices, and the level of available housing inventory.


In Guelph and the surrounding communities, local real estate conditions remain an important part of the picture. Interest rates are one factor among several that can influence buyer activity and the pace of the housing market.


Looking Ahead: The Next Bank of Canada Rate Announcement


The Bank of Canada's next scheduled interest rate announcement is December 9, 2026. The next Monetary Policy Report is scheduled for release on January 27, 2027.


Until then, the Bank will continue monitoring inflation, economic growth, labour market conditions, energy prices, and developments in Canada-US trade relations.


The latest announcement reflects the Bank's efforts to address persistent inflation while supporting the Canadian economy through a period of continued uncertainty.


For anyone following the housing market, the upcoming months will provide more insight into how economic conditions and interest rate decisions may influence real estate activity.


Have questions about how this may impact your buying or selling plans? Contact us today to discuss your next steps in today's market.

Share This Article
September 28, 2026
Join us October 16th for a Special Night of Hockey & Heart Last year, we raised over $10,000 for local wish kids. This year, we’re aiming to do even more! On Friday, October 16, the Storm’s Cause Marketing Game, sponsored by Coldwell Banker, will donate 50/50 proceeds to the Guelph Wish Fund for Children. For over 40 years, the Guelph Wish Fund has helped children in Guelph and Wellington County facing serious illness, medical challenges, or significant disabilities—creating moments of joy, hope, and unforgettable memories for them and their families. Every ticket helps make a difference for a local child. Join us in supporting these young heroes, both on and off the ice.
September 22, 2026
As of September 21, 2026, Ontario's rental landscape has shifted in meaningful ways. Whether you own an investment property, rent out a basement unit, or are a tenant in Guelph and the surrounding area, these updates affect how tenancies are managed, how disputes are resolved, and how quickly timelines move. Here is a clear overview of what has changed and what it means for you. The Background The second wave of amendments under Bill 60 and Bill 97 took effect on September 21, 2026, introducing shorter eviction timelines, a codified definition of habitually late rent, financial prerequisites for raising certain issues at hearings, and revised compensation rules for personal use evictions. These follow an earlier round of changes that came into force on July 1. The province's stated goal is to reduce backlogs and speed up disputes at the Landlord and Tenant Board (LTB). Immigration News Canada Unpaid Rent: A Shorter Notice Period When rent goes unpaid, a landlord serves an N4 notice. For an N4 given on or after September 21, 2026, the notice period has been shortened from 14 days to 7 days. Any N4 served before that date must still use the previous 14 day period to be legally valid. A Clear Definition of Persistent Late Payment For the first time, the rules spell out what "persistently late" means. A tenant can now be considered persistently late if they fail to pay rent within seven days of the due date on at least three separate occasions within six months. This gives landlords a specific standard when documenting late payments and pursuing an N8 notice. For tenants, repeated late payments can now create a clearer basis for a landlord to seek to end a tenancy, even if the rent is eventually paid. blogTO MoneySense New Conditions at Non Payment Hearings Tenants facing an arrears hearing have traditionally been able to raise their own concerns, such as maintenance problems, harassment, or illegal entry. For landlord applications made on or after September 21, 2026, a tenant who wants to raise those issues at the hearing must generally pay 50% of the rent arrears claimed. Applications filed before that date continue under the previous rules, even if the hearing happens later. That payment must be made no later than seven days before the hearing. CanooqCanooq Own Use Evictions: A New 120 Day Option Previously, a landlord ending a tenancy so that they or a close family member could move in had to file an N12, give at least 60 days' notice, and pay one month of rent as compensation. Landlords now have a choice. They can continue using the 60 day process, or provide at least 120 days' notice and avoid paying that compensation. NOW Toronto blogTO There are important conditions. To qualify, the N12 must be given on or after September 21, the termination date must be at least 120 days later, and it must fall at the end of a rental period or fixed term. The waiver also has limits: notices where a purchaser intends to move in remain subject to the existing one month compensation requirement. This matters for anyone selling a tenanted property, since the buyer's move in does not qualify for the new exemption. Immigration News CanadaImmigration News Canada The province has also added safeguards against misuse. The landlord or other person named on the N12 must generally occupy the unit within 60 days of the date on the notice. If they do not, the former tenant can bring a bad faith eviction application, and the N12 is presumed to have been given in bad faith unless the landlord can rebut the claim. Moving2Canada Renovations and the Right to Return Some of the new rules give tenants additional rights if they are asked to leave for major renovations or repairs. A tenant who states in writing that they want to return after the work is finished triggers a process the landlord must follow. Moving2Canada Changes That Took Effect July 1 Several updates have already been in place since the summer. For an LTB order issued on or after July 1, 2026, a request to review must generally be made within 15 days rather than 30. Tenants also gained the right to install a window or portable air conditioner with written notice, a mandatory LTB Payment Agreement Form was introduced for repayment plans, and maximum fines doubled to $100,000 for individuals and $500,000 for corporations. Powerhousepm OntarioLandlord What Has Not Changed Two points are worth emphasizing. First, an eviction notice still does not allow a landlord to personally remove a tenant or change the locks. Where an eviction order is required, the landlord must apply to the LTB and follow the legal enforcement process. Second, rent control remains in place. The 2026 rent increase guideline is 2.1% for most rent controlled tenancies, and landlords must generally provide at least 90 days' written notice. Many units first occupied after November 15, 2018 may be exempt from the guideline. Canooq Powerhousepm Practical Steps For landlords, now is the time to update your forms, keep a detailed rent ledger, and review any N12 carefully before serving it, particularly if a sale is involved. For tenants, setting up automatic payments, keeping records of all communication with your landlord, and understanding your rights around renovations and own use notices will help you stay protected. We're Here to Help If you own a rental property, are considering an investment purchase, or are weighing whether to sell a tenanted home, these changes can affect your timing and your strategy. The team at Coldwell Banker Neumann Real Estate is happy to walk you through how the new rules apply to your situation.  This article provides general information only and does not constitute legal advice. For guidance on a specific tenancy matter, please consult a licensed paralegal or lawyer.
September 22, 2026
If you have boxes of old tax returns, bank statements, or paperwork piling up in the basement, here is your chance to clear them out safely and support your community at the same time. Crime Stoppers Guelph Wellington is hosting a shredding event this Saturday, September 26, right here in Guelph. Event Details Date: Saturday, September 26 Time: 9am to 12 noon (or until truck capacity is reached) Location: 201 Woodlawn Rd. W., Guelph Cost: $10 per box (banker box size) All proceeds go directly to Crime Stoppers Guelph Wellington. Why Shredding Matters Identity theft often starts with something as simple as a discarded bill or an old bank statement. Documents with your name, address, account numbers, or signature can be valuable to the wrong person. Tossing them in the recycling bin is not enough. Secure shredding is one of the easiest ways to protect yourself and your family. This event makes it simple. Mobile shredding services are provided by Republic Services, so your documents are destroyed on site. The event is hosted and supported by Skyjack at their Woodlawn Road location. What to Bring Think about the paperwork you no longer need but should not throw away as is: old tax records past the required retention period, bank and credit card statements, pay stubs, medical and insurance paperwork, old utility bills, and any documents with personal or financial information. If you are getting ready to move, downsizing, or just finally tackling that storage room, this is a great opportunity to lighten the load before the season changes. A Tip Before You Go The event runs until noon or until the truck is full, so arriving early is your best bet. Pack your documents in banker size boxes to keep things moving quickly at drop off. Supporting Crime Stoppers Guelph Wellington Crime Stoppers Guelph Wellington helps keep our community safe by allowing people to share information about crime anonymously. Every $10 box you bring helps fund that work. To learn more or to submit an anonymous tip, visit www.csgw.tips or call 1 800 222 TIPS (8477). Clear the clutter, protect your identity, and support a great local cause. We hope to see you there on Saturday!
September 16, 2026
As the leaves begin to change and the air gets a little cooler, Guelph becomes a beautiful place to get outside and enjoy the season. Whether you're looking for a peaceful walk through colourful trees, a fun family outing, or a classic pumpkin-filled fall experience, there are plenty of ways to enjoy autumn right here
September 2, 2026
On September 2, 2026, the Bank of Canada announced that it is maintaining its target for the overnight rate at 2.25%, with the Bank Rate at 2.50% and the deposit rate at 2.20%.
Pumpkins on hay
By At The Puslinch Community Centre • August 17, 2026
Get ready for a weekend of family fun, community spirit, and harvest-time traditions at the 184th Annual Aberfoyle Fall Fair , happening September 11 and 12, 2026 , at the Puslinch Community Centre. This year’s theme, “It’s Harvest Time!” , sets the stage for a celebration packed with entertainment and activities for all ages. The fun includes giant inflatables, a rock climbing wall, axe throwing, live music, delicious food vendors, live pets, the famous Antique Tractor Pull, and so much more! Families can also enjoy the spectacular Marvels & Misfits Fire Show and an all-ages Glow Stick Dance Party, while adults can unwind in the licensed Refreshment Tent.  Get Creative for the Display Contest for a Chance to WIN! The fair is also inviting families, friends, neighbours, and coworkers to get creative and help spread the word by putting together a festive harvest-themed display at their home or business. Whether you’re showcasing your garden harvest, creating a fall scene, or bringing your own creative twist to the theme, it’s a great way to bring the community together and build excitement for fair weekend. There are cash prizes up for grabs: 🥇 1st Place: $125 🥈 2nd Place: $100 🥉 3rd Place: $75 All displays must include signage with: Aberfoyle Fall Fair – September 11th & 12th, 2026 – at the Puslinch Community Centre To enter, email Jill Robbers at jillrobbers@gmail.com with your name, contact information, and display address by September 4, 2026 . For 184 years, the Aberfoyle Fall Fair has celebrated agriculture, community, and family traditions. This September, come out and be part of the tradition—make memories, support the community, and celebrate together. Coldwell Banker Neumann is proud to be a sponsor of the Aberfoyle Fall Fair and to support this wonderful community tradition. 📅 September 11 & 12, 2026 📍 Puslinch Community Centre ⏰ Gates open at 5pm on Friday, and 9am on Saturday Come celebrate the harvest and discover everything the Aberfoyle Fall Fair has to offer!
July 16, 2026
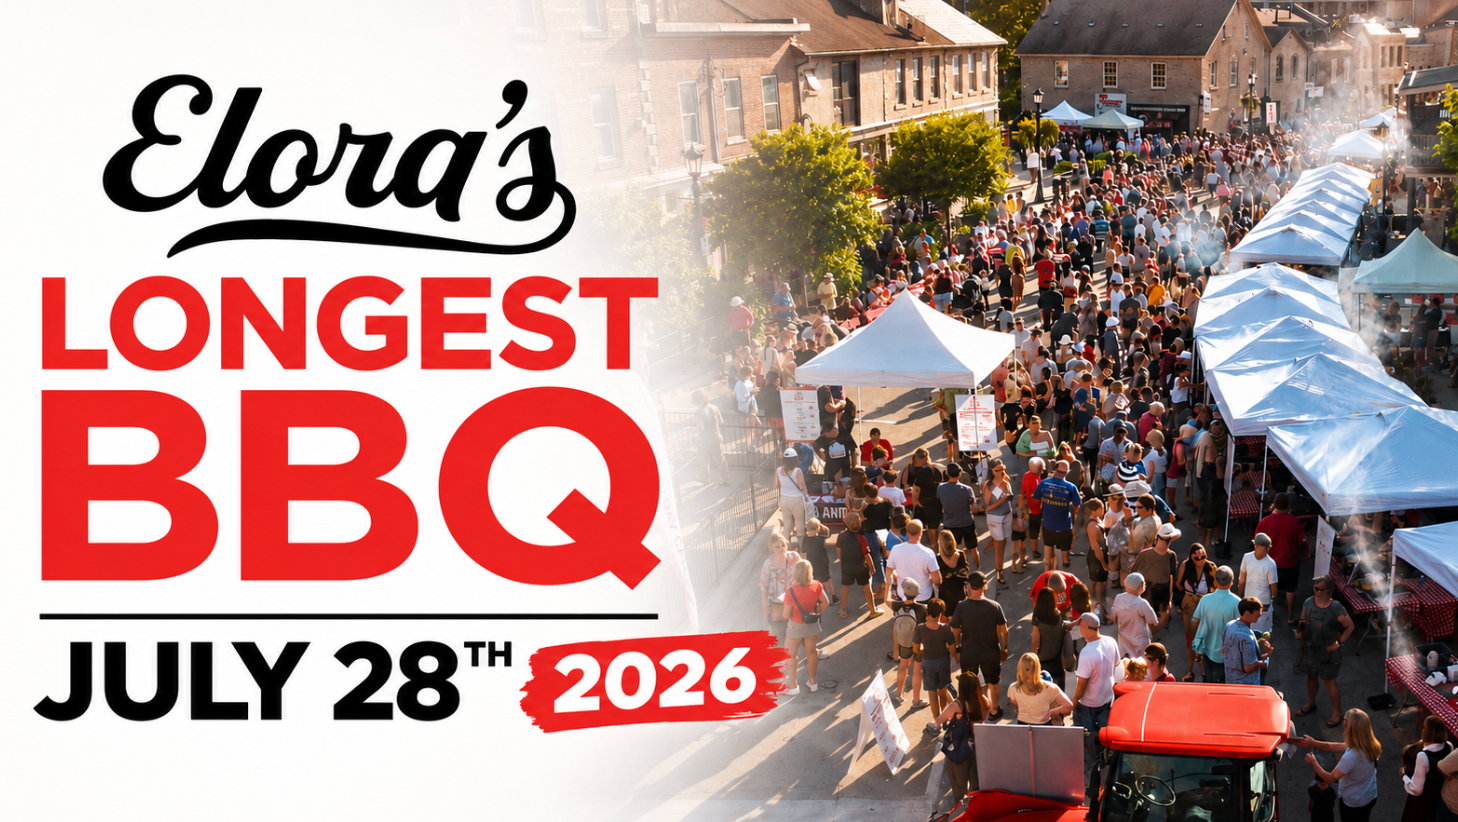
Tuesday, July 28, 2026, Elora's Longest BBQ returns to historic downtown Elora for an evening filled with incredible Canadian cuisine. Food Day Canada.
July 15, 2026
Bank of Canada announced it is maintaining its target for the overnight rate at 2.25%, with the Bank Rate at 2.50% and the deposit rate at 2.20%.
Jeff Neumann reflects on his early real estate career, the evolution of MLS access, and why trust, e
By Jeff Neumann • June 17, 2026
Jeff Neumann reflects on his early real estate career, and why trust, expertise, and adaptability—not information alone—remain the foundation of long-term success.
June 10, 2026
On June 10, 2026, the Bank of Canada announced it is maintaining its target for the overnight rate at 2.25%, with the Bank Rate at 2.50% and the deposit rate at 2.20%. The decision comes as global uncertainty persists, driven by ongoing geopolitical conflict, energy market volatility, and continued trade policy tensions. Rising oil prices and supply chain disruptions are contributing to inflationary pressure while also weighing on global economic growth. Global Economic Trends Remain Generally Steady In the United States, growth remains solid, supported by consumer spending and AI-related investment. In contrast, the euro area continues to see weaker growth as higher energy costs weigh on activity. China’s economy remains more stable, supported by strong export demand. Global financial conditions have loosened since the last Monetary Policy Report, with strong equity markets and continued volatility in bond yields. The Canadian dollar has also weakened against the US dollar and other major currencies. Canadian Economy Shows Soft Momentum Recent data shows the Canadian economy contracted slightly in the first quarter, with GDP edging down by 0.1%. While consumer spending increased, declines in government spending, housing activity, business investment, and exports weighed on overall growth. Employment increased in May, but overall labour market conditions remain soft, with unemployment holding between 6.5% and 7%. Even with expected near-term improvements, the economy is still projected to operate with excess supply. Inflation Remains Elevated but Moderating CPI inflation rose to 2.8% in April, largely driven by higher energy prices, including oil and the removal of the consumer carbon tax from the year-over-year comparison. Core inflation has eased closer to 2%, and broader price pressures remain more contained. Food inflation has moderated but remains elevated, while shelter inflation continues to ease. Overall inflation is expected to remain near 3% in the near term before gradually moving back toward the Bank’s 2% target. Policy Decision And Outlook Against this backdrop, the Governing Council decided to maintain the policy rate at 2.25%. The Bank noted ongoing weakness in domestic growth, persistent global uncertainty, and elevated energy prices. While it continues to look through short-term inflation impacts from energy, it emphasized it will not allow these pressures to become entrenched in long-term inflation trends. The Bank remains committed to supporting price stability and will respond as needed as economic conditions evolve. Looking Ahead  The next scheduled announcement for the overnight rate is July 15, 2026, when the Bank will also release its next Monetary Policy Report. Until then, borrowing conditions are expected to remain relatively steady as markets continue to adjust to evolving global and domestic economic signals. Have questions about how this may impact your buying or selling plans? Contact us today to discuss your next steps in today's market.
More Posts